Why is a Police Case Number Required After a Motor Vehicle Accident?
May 29, 2026
Chimney fire insurance claims: what Garden Route homeowners should know this winter
July 20, 2026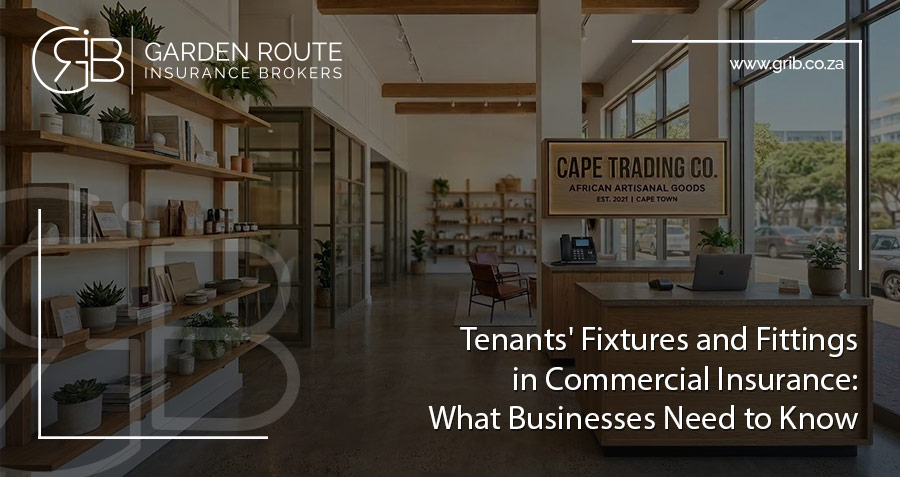
In building insurance, tenants’ fixtures and fittings refer to items installed or added by a tenant in a rented property that are considered part of the building for purposes of insurance. These would typically include signs or advertising boards, partition walls added by the tenant, carpeting or flooring installed by the tenant, or built-in display units in commercial properties.
While these additions may seem straightforward, tenants’ fixtures and fittings can create confusion when it comes to commercial insurance. Understanding how they are classified and insured is essential for both tenants and property owners to avoid disputes and ensure adequate protection in the event of loss or damage.
What Are Tenants’ Fixtures and Fittings?
Tenants’ fixtures and fittings are improvements or alterations made by a tenant to a leased property to better suit their business operations. Unlike movable equipment or furniture, these items are typically attached to the building and cannot be easily removed without causing damage.
Common examples include:
- Interior partitioning or office cubicles
- Built-in shelving and display counters
- Custom flooring or carpeting
- Air-conditioning units installed by the tenant
- Signage attached to the building
- Fixed lighting installations or decorative fittings
These fixtures become part of the premises while the tenant occupies the space, but the responsibility for insuring them is not always automatically clear.
Who Is Responsible for Insuring Tenants’ Fixtures and Fittings?
One of the most important aspects of tenants’ fixtures and fittings is determining who is responsible for insuring them, the landlord or the tenant.
In many commercial lease agreements, the landlord insures the building structure, while the tenant is responsible for insuring improvements they have made to the premises. This means that fixtures installed by the tenant may not automatically be covered under the landlord’s building insurance policy.
As a result, tenants often need to insure these additions under their own commercial insurance policy, usually as part of the Fire or Buildings Combined sections.
Why Proper Insurance Matters
If tenants’ fixtures and fittings are not properly insured, businesses could face significant financial loss after events such as fire, storm damage, malicious damage, or theft.
For example, a retail store may install custom shelving, flooring, and branded signage to create a distinctive customer experience. If a fire damages the premises, the landlord’s building policy may only cover the original structure, not the tenant’s additions. Without proper cover, the tenant would have to pay for these improvements out of their own pocket.
Avoiding Insurance Gaps
To prevent misunderstandings or coverage gaps, businesses should take a few important steps:
Review the lease agreement carefully
Commercial leases often specify which party is responsible for insuring improvements to the property.
Discuss cover with an insurance broker
A broker can help ensure that tenants’ fixtures and fittings are properly included in the policy schedule and insured for the correct value.
Keep records of improvements
Invoices, photographs, and installation documents can be useful when determining the replacement value of these fixtures.
Ensure adequate sums insured
As businesses upgrade or expand their premises, the value of tenant-installed improvements may increase over time.
Tenants’ fixtures and fittings play an important role in shaping commercial spaces and supporting business operations. However, they also introduce potential complexities when it comes to insurance cover. Both tenants and landlords should clearly understand who is responsible for insuring these additions.
Whether you’re a business owner renting commercial space or a landlord managing a portfolio of properties – knowing exactly what your insurance policy covers can prevent a painful surprise after a claim.
At Garden Route Insurance Brokers, we review your lease and your existing cover together to make sure your tenants’ improvements are properly protected. Get in touch and let’s make sure nothing slips through the cracks.
Sandra Anderson – Claims Team Leader, Garden Route Insurance Brokers
Garden Route Insurance Brokers is an authorised Financial Services Provider (FSP 15438)